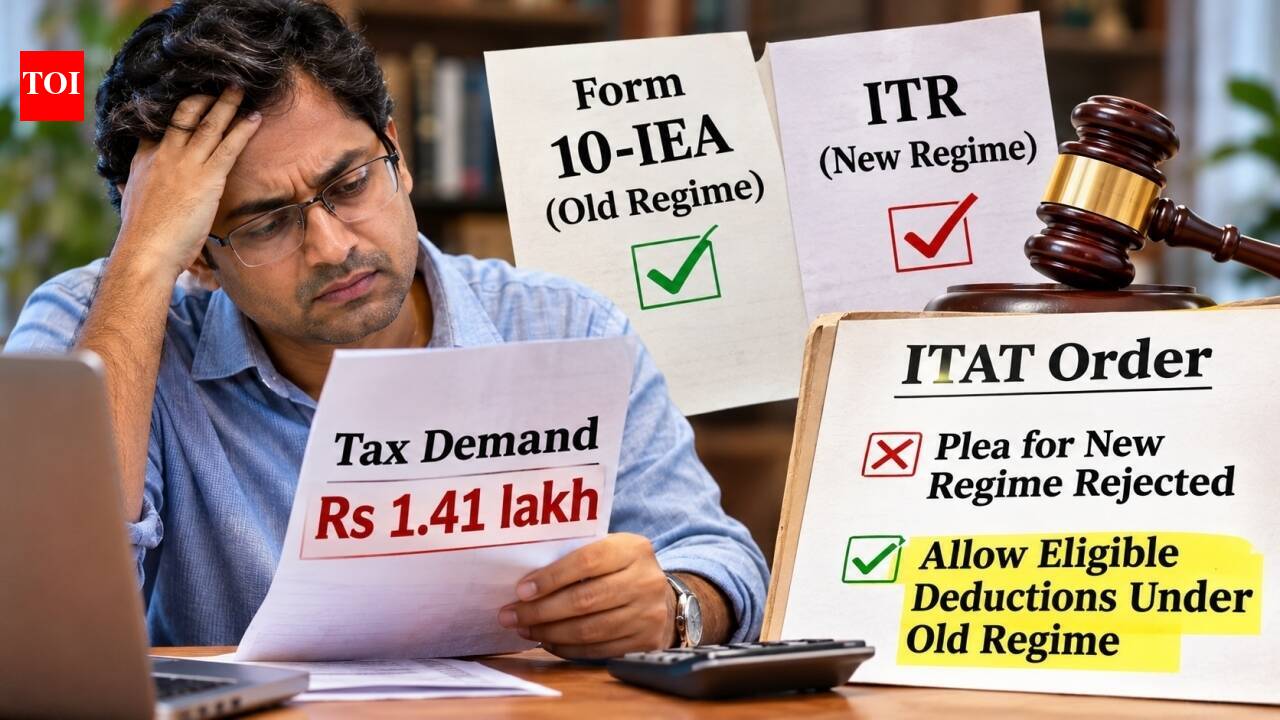
Taxpayer filed Form 10-IEA for old regime but selected new regime in ITR, resulting in demand of Rs 1.41 lakh; ITAT rejects its plea for new regime but asks taxman to allow appropriate deduction under old regime
You opt out of the new income tax system by filing Form 10-IEA, but while filing your income tax form opt out of the new system. Under which regime will your return be processed – new or old?In one such case the taxpayer ended up making the wrong decisions and the Income Tax Department processed his return under the old tax system and raised the demand for tax. He fought against the addition of tax believing that his choice in ITR should override Form 10-IEA.The Income Tax Appellate Tribunal (ITAT), Mumbai, rejected the taxpayer’s contention that the selected return should be valid. However, it gave him partial relief. Read on to find out what happened.
What is the case about
The case is about the income tax return of the husband for the assessment year 2025-26. The taxpayer opted for a new income tax scheme in the previous assessment year, 2024-25. On August 31, 2025, when he filed the 10-IEA form he withdrew from the new regime and was taxed under the old income regime.However, when he filed his income tax return on September 16, 2025, declaring an income of Rs 33,88,170, he chose an option indicating that he did not wish to opt out of the new tax regime. This was contrary to the choice written on the form he had submitted earlier.The CPC processed his return under Section 143(1) of the Income-tax Act, 1961, on January 29, 2026. It considered Form 10-IEA and suggested a demand of Rs 1,41,480. Joshi sought redress, but the CPC rejected his plea under Section 154 on February 17, 2026.He then appealed to the Commissioner of Income Tax (Appeals), who agreed to the settlement. The appellate authority has reasoned that the taxpayer has withdrawn from the new tax system using the prescribed form, making the contrary choice and his return a wrongful claim.Before the Mumbai ITAT, the taxpayer argued that the CPC should have followed the elective option in its return instead of relying on Form 10-IEA. His counsel cited the decision of the Pune ITAT Akshay Nitin Malu v. Tax Officerthey say that the choice announced in the letter should be respected.He also challenged the processing of his reinstatement on the grounds that the CPC did not issue advance warning of the proposed amendment. For this, he relied on the decision of the Bombay High Court Rallis India Ltd v. Central Processing Center.Alternatively, the man argued that if the old tax regime applies because of Form 10-IEA, he should be allowed the deductions available under that regime. His claims include Rs 1.5 lakh under Section 80C, Rs 50,000 under Section 80D and Rs 50,000 under Section 80TTB.
What ITAT Mumbai says
The court examined whether the taxpayer could rely on his election if he objected to the prescribed form he had already filed.The bench noted that the taxpayer opted for the new income tax scheme for the assessment year 2024-25 and then filed Form 10-IEA to switch over to the old income tax scheme for the assessment year 2025-26.Under Section 115BAC, taxpayers with business or professional income must exercise the relevant option in a prescribed manner, and the rules set limits on when that option can be withdrawn.The tribunal concluded that the chosen reference could not exceed the prescribed form.It noted: “In our opinion, once a certain form has been determined to opt out of the new tax system, the assessee cannot be allowed to choose the new tax system unless he fills out the specified form under the provisions of the Act.”It also set aside the decision of the Pune ITAT cited by the taxpayer. In that case, the taxpayer had filed Form 10-IE to withdraw from the new regime and had also filed a return under the old regime.This case was different because the form and return showed conflicting choices. The court observed: “But suddenly, the facts are different. In the 10-IE form filed, the assessee opts out of the new tax system and opts for the old tax.” But in the refund, the wrong box is ticked. “The bench also rejected the taxpayer’s argument that the CPC processed his return without prior notification. It had asked him to produce evidence from the income tax portal showing that no notice was sent by email or physical letter, but he did not provide the material requested.The court separated them Rally India case because the department admitted there that no notice or proposed correction was issued. It therefore dismissed this ground of appeal.The taxpayer, however, succeeded in his other claim regarding the deduction. The court said that if the old income tax regime is applicable on the basis of Form 10-IEA, the deductions available under that regime should also be taken into account.It noted: “If the CPC holds that the assessee has opted out of the new tax regime and the old tax regime is applicable, then the deductions entitled under the old tax regime should be allowed to the assessee.The bench set aside the order of appeal on this limited issue and remanded the matter to the Assessing Officer to assess the appropriate deductions. The tribunal also wrote that “In our view, there is merit in the submission of counsel.”The ITAT issued its order on September 17, 2026, and partially allowed the appeal. It did not directly cancel the demand of Rs 1,41,480 or automatically grant all the deductions. The Assessing Officer has to assess the taxpayer’s eligibility for deduction under the old law.
Source link