The wife buys a property for Rs 1.4 crore and the Dubai-based husband pays Rs 80 lakh directly into the seller’s account, but receives a tax notice for an unexplained investment; why ITAT Mumbai is in favor of him
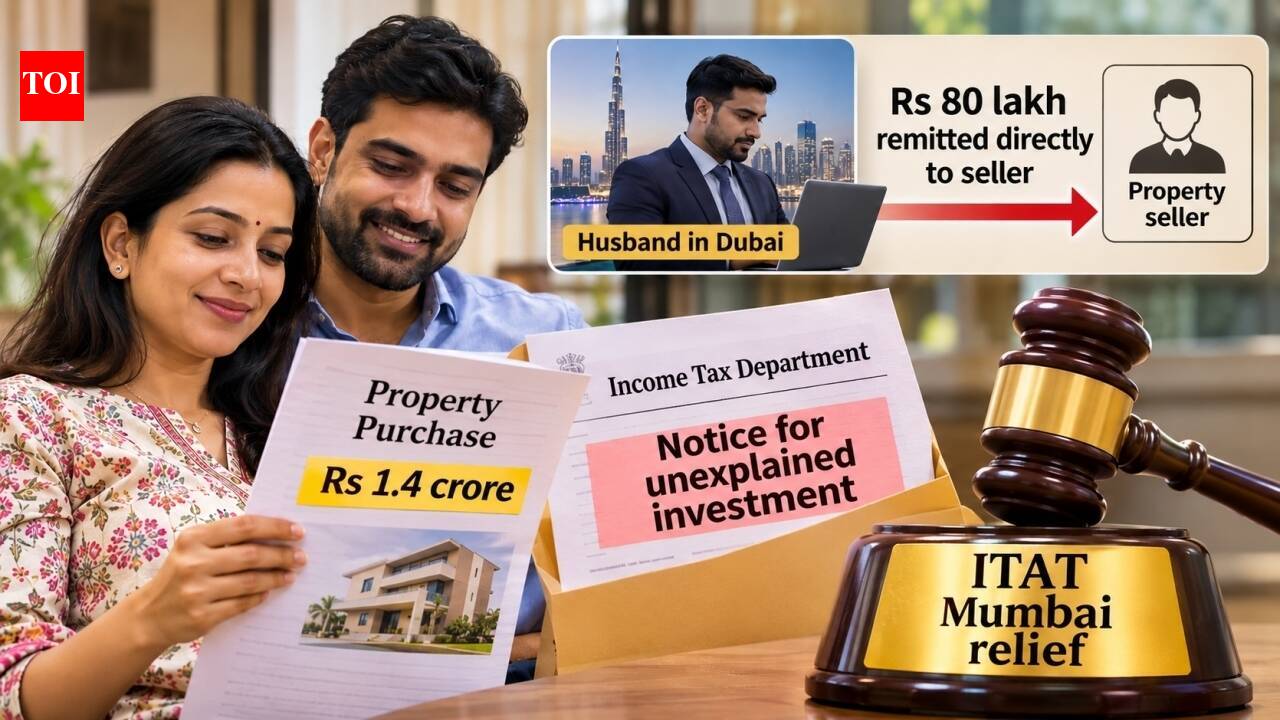
You buy a property, part of which is financed by your husband who lives abroad and you withdraw money from the seller’s account. But the Income Tax Department considers it as a non-deductible investment and adds it to your taxable income. What are you doing?In one such case, the taxable income of a Mumbai woman went up by Rs 80 lakh after the tax department questioned the amount paid for the purchase of her residence.The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) ruled in favor of the woman. Read on to find out what happened:
What is the case about
According to the IT department’s ‘Insight Portal’, the woman purchased an immovable property worth Rs 1.4 crore in the financial year ended March 31, 2016.The portal monitors high-value financial transactions to help detect cases of tax evasion. The case was about Section 69 of the Income Tax Act, 1961, which deals with unexplained investments.The information is from the office of the sub-registrar and was verified by the data available from the tax deducted at source (TDS) statement related to the transaction.The woman had not filed her income tax return, proceedings were initiated under Section 148A. Then he submitted his return letter.She explained that the investment was financed by the profit from the sale of the previous building and financial assistance from her husband who lived and worked in Dubai.During the inspection, the Assessing Officer inspected the registered sale deed, Form 26AS and the bank accounts of the woman and the seller. After calculating the TDS of Rs 1.40 lakh, the payment to the estate came to Rs 1,38,60,000.The official accepted payments amounting to Rs 58.50 lakh. This includes Rs 40 lakh paid on August 12, 2015, and Rs 18.50 lakh paid on August 26, 2015, which are reflected in the woman’s bank account and correspond to entries in the merchant’s account.The remaining Rs 80 lakh has been disputed. The woman said her husband paid the money directly to the seller through the Dubai exchange office in two installments of Rs 40 lakh each. The merchant’s bank statement recorded two credits totaling Rs 80 lakh.However, the Inspector said that this account did not reveal that the money came from the husband. She also noted the absence of remittance advice, exchange office records, money transfer instructions and bank statements showing withdrawals from the husband’s account.As a result, Rs 80 lakh was treated as undisclosed investment. Another Rs 10,000 was added as unexplained balance consideration, taking the additional sum to Rs 80.10 lakh.The Commissioner of Income Tax (Appeals) has upheld the additions. He then challenged the order at the ITAT Mumbai and got relief
Why did the ITAT favor this woman
Appearing before the ITAT, the woman argued that she had adequately explained the source of the entire Rs 1.4 crore investment and supported her claim with documentary evidence.She gave a detailed reconciliation of the purchase price of the property, accounting for all parts of the payment, including the Rs 80 lakh transferred by her husband to the seller.To prove her case, she submitted a registered sale deed, a gift deed executed by her husband, an affidavit confirming the payments, bank statements and other relevant documents. These records, he kept, established the flow of money and proved that the transactions were genuine.The court examined the documents collectively instead of taking the absence of original remittance records as determinative. It noted that the purchase, the registered sale deed, the seller’s ownership and the receipt of the consideration were not contested.As the order stated: “There is no dispute regarding the purchase of residential property by the assessee for consideration of Rs.1,40,00,000/-.”The court also observed that neither the Assessing Officer nor the Commissioner of Income Tax (Appeals) found the documents submitted by the woman to be false, forged or manipulated. The seller’s bank statement shows the disputed credits, while the husband’s affidavit confirms that he paid her. His identity cards and income tax records were also placed before the court.It noted: “These evidences are not isolated documents but linked and supporting evidences that jointly establish the source and distribution of the funds involved in the real estate transaction.”Also thought to be remittance records related to work done nearly a decade earlier. The court found that the authorities did not conduct an investigation with the seller or collect bad material from the bank to establish that the payments represented the woman’s unknown money.The order said: “More importantly, no authority has ever written anywhere to find that the documents provided by the assessee are false, forged, fraudulent or otherwise unauthentic.”The court held that this explanation could not be rejected simply because more and more evidence was not available when other documents supported the transaction.It concluded: “Suspicion, no matter how strong, cannot take the place of evidence, especially when the surrounding facts and recorded material fully support the explanation given by the examiner.”It held that the woman discharged the burden under Section 69 by finding out who contributed, financial strength, source of funds and their use in purchasing the property. The court then directed the Assessing Officer to remove the entire excess of Rs 80.10 lakh.The appeal was allowed.
Source link