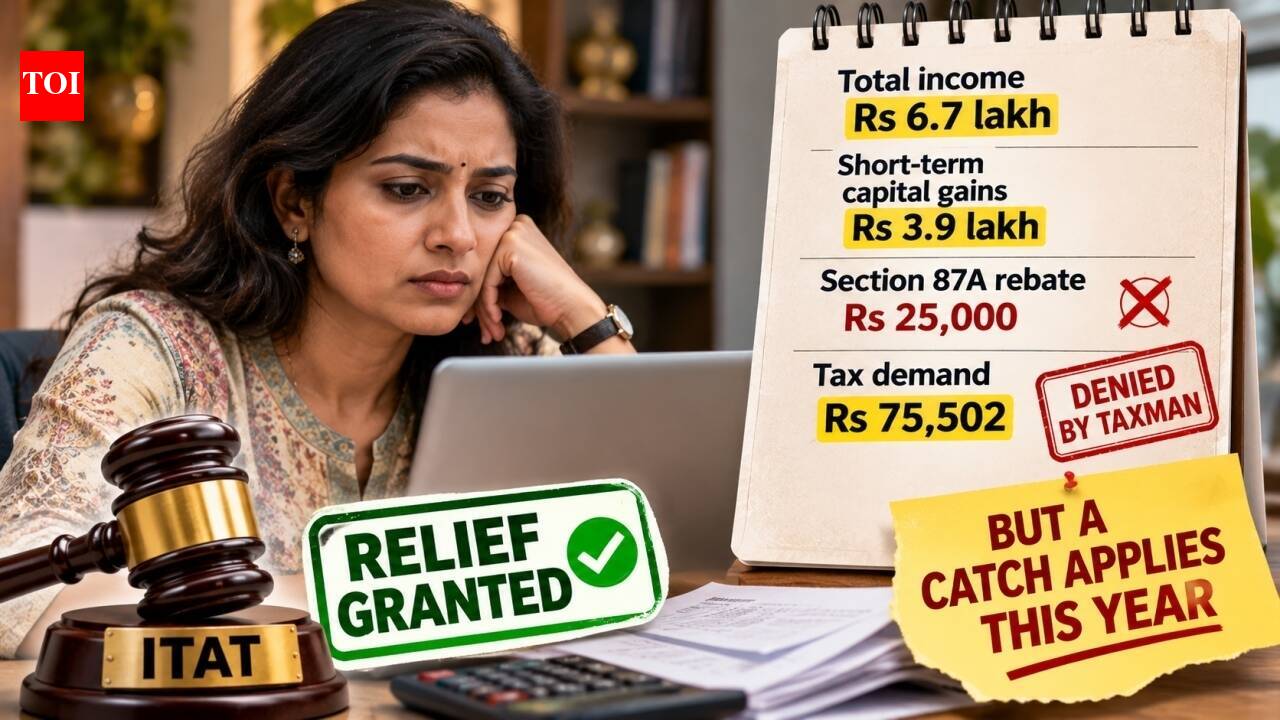
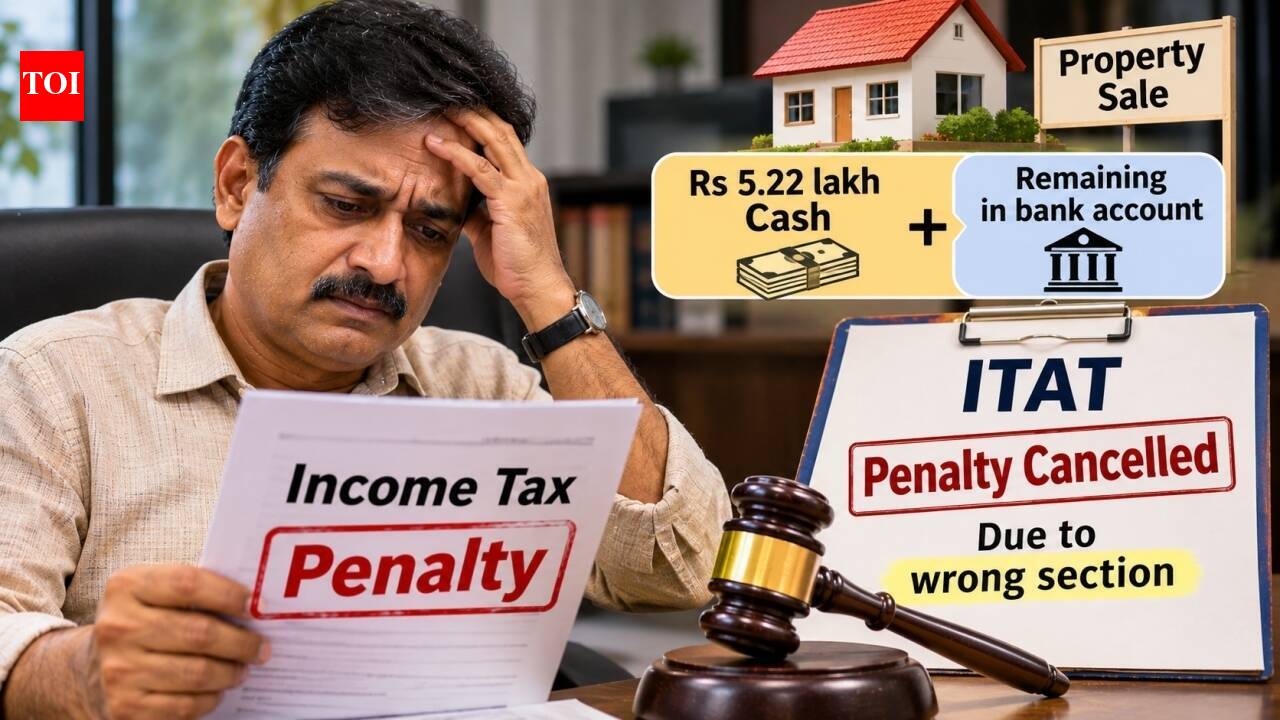
A person sells a property and takes cash of Rs 5.22 lakh and the balance is in a bank account, he faces income tax penalty on exchange of money; The ITAT cancels it because the tax officer has applied the wrong section
In the case of property deals, cash transactions are allowed up to a certain limit. What if you sell the property and participate in cash and the Tax Department imposes a penalty?In another case, the assessee faced a tax penalty but was able to get relief, but for technical reasons. Read on to find out why the Income Tax Appellate Tribunal (ITAT) ruled in favor of the local seller.
What is the case about
The owner of the property sold it and received a sum of Rs 5.22 lakh while the remaining amount was credited to his bank account. Income tax provisions prohibit the receipt of more than Rs 2 lakh from such transactions.The Income Tax Assessing Officer (AO) in Berhampur received information from the land registrar’s office in Jharsuguda that the man had sold the property and collected Rs 5.22 lakh as part of the payment. The registered deed also mentioned part of the money.After this information, the AO issued a notice to the man under Section 269SS of the Income Tax Act and imposed a penalty under Section 271DA.The Income Tax Appellate Tribunal (ITAT), Cuttack, granted relief to the man.
Why did the ITAT favor the property seller?
Appearing for the man before the ITAT Cuttack, his counsel argued that the AO relied on Section 269SS to treat the cash received as trade consideration as a violation of income tax law.However, the lawyer asserted that Section 269ST, which came into force from AY 2017-18, was a provision applicable to this particular violation.To substantiate his argument, the lawyer referred to the previous decision of ITAT Cuttack in the case of Arati Saraf (ITA No. 375/CTK/2023), dated 13th May, 2024.He drew the court’s attention to the judgment of the ITAT Cuttack in the Arati Saraf case, where the court had examined a similar issue.In that matter, the Assessing Officer applied Section 269SS of the Income Tax Act and imposed penalty under Section 271D on the proceeds of sale of immovable property.However, Section 269ST and 271DA were introduced to deal with violations involving cash transactions exceeding Rs 2 lakh.Counsel contended that the AO failed to apply the relevant provisions in this case, even though the duty falls under Section 269ST.In its decision in the Arati Saraf case, the ITAT Cuttack also explained the legislative intent behind the provision.The panel referred to the memorandum and notes on the clauses accompanying the Finance Bill, 2015, which made it clear that the amendment was intended to curb the creation of black money in real estate transactions by prohibiting the acceptance of specified cash funds.It noted that the term “specified sum” applied only to “before” acquisitions, while the phrase “before” meant that improvements could take any form.The tribunal further stated in Arati Saraf’s case that the conditions do not apply where no cash proceeds have been received and the cash payment is made at the time of registration of the deed.Arati Saraf’s case fell into this category because, as admitted, the entire amount had been received in one payment on the issuance of the deed. ITAT Cuttack therefore concluded that Section 269SS was not violated and was not applied improperly in that transaction.In this matter, the ITAT Cuttack relied on the reasoning in Arati Saraf and found that the facts clearly showed that Section 269SS was not applicable to the conduct in which the AO had imposed penalty under Section 271D.The court observed: “This is so, respectfully following the decision of the connecting bench of this Bench in the case of Arati Saraf as in Satyabrata Panda, as it is noted that the AO applied the provisions of Section 269SS in this case instead of applying the provisions of Section 269ST; therefore, the sentence is set aside under Section 27D.”1As a result, on October 5, 2026, the ITAT Cuttack ruled in favor of the man and canceled the fine.
Source link